2-minute home check
How much house can you actually afford in DFW?
Answer 9 quick questions. See your price range and your real monthly payment, Texas property taxes included.
What are you looking to do?
Pick the one that fits best.
When do you want to move?
No wrong answer. Starting early is smart.
What's your credit score, roughly?
A guess is fine. This doesn't check your credit.
Have you served in the military?
Veterans and active duty can often buy with 0% down.
How do you get paid?
If two of you are buying, pick the main earner.
What's your yearly household income?
Before taxes. Add everyone who'll be on the loan.
What do you pay each month in debts?
Car, credit card minimums, student loans. Don't count rent, phone, or utilities.
How much have you saved to buy?
For down payment and closing costs. Include gift money if you have it.
What's your current mortgage rate?
It's on your monthly statement.
About how much do you still owe?
Your current loan balance. A rough number is fine.
Where in DFW?
Property taxes change a lot from city to city.
Your results are ready.
Where should I send them? I'll also look over your answers myself and text you if I spot a better option.
Estimates only, not a loan approval, rate quote, or commitment to lend. Assumes a 30-year fixed loan with a conservative estimated rate, DFW property tax rates before exemptions, and typical insurance. Your real numbers depend on your credit, the home, and the loan program.
How much house can you afford in DFW?
Most online calculators only look at your income. In Texas that leaves out a big piece of the payment: property taxes. With no state income tax, DFW cities lean on property taxes, and rates run about 1.6% to 2.4% of the home's value per year. On a $350,000 home that can be $500 to $700 a month on top of your mortgage.
This quiz works backward from what you can comfortably pay each month, including taxes, insurance, and mortgage insurance, to a price range that fits. The low end keeps your total monthly debts near 36% of your income before taxes. The high end is about 45%, which is close to the limit most lenders allow.
Example: a first-time buyer in Mansfield earning $100,000 a year, with $500 a month in car and card payments and $30,000 saved, lands around $270,000 to $345,000, with a full monthly payment of about $3,250 at the top of that range.
What changes your number the most
- Your monthly debts. Every $100 a month in payments lowers your budget by roughly $10,000 in home price.
- Which city. The same payment buys more house in Frisco or McKinney than in Mansfield or Burleson, because of lower tax rates.
- Your loan program. VA loans need 0% down with no monthly mortgage insurance. FHA allows 3.5% down with lower credit. Bank statement loans help if you're self-employed.
- Your credit. A higher score usually means a lower rate, which means more house for the same payment.
Common questions
Does this quiz check my credit?
No. Nothing about the quiz touches your credit. It uses the ranges you pick to give you an estimate. A real pre-approval is the step where credit gets reviewed, and I'll always tell you before that happens.
How much house can I afford on a $100,000 salary in DFW?
With $500 a month in other debts and 3–5% down, roughly $270,000 to $345,000 in a city like Mansfield, once property taxes, insurance, and mortgage insurance are included. Lower debts or a lower-tax city push that number up.
What is debt-to-income ratio (DTI)?
It's the share of your monthly income before taxes that goes to debt payments, including your new house payment. If you earn $8,000 a month and your debts plus mortgage total $3,200, your DTI is 40%. Most loans allow up to about 45–50%.
How much do I need for a down payment in Texas?
VA loans: 0%. FHA: 3.5%. Conventional: as little as 3% for first-time buyers and 5% for repeat buyers. Plan for closing costs too, usually 3–5% of the loan, which seller credits or down payment assistance can help cover.
Is this the same as being pre-approved?
No. The quiz is an estimate to help you plan. A pre-approval means a lender has reviewed your income, assets, and credit, and it's what you'll need to make an offer. Getting pre-approved with me is free, and I move fast on it.
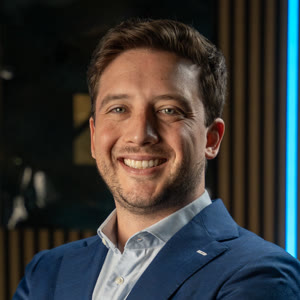
I'm Matthew Parra, a mortgage broker with Hometown Lending based in Mansfield, TX. I shop 50+ wholesale lenders for every client and I answer my phone. More about me →